
Going Infinite Summary: Key Lessons for Real Estate Leaders
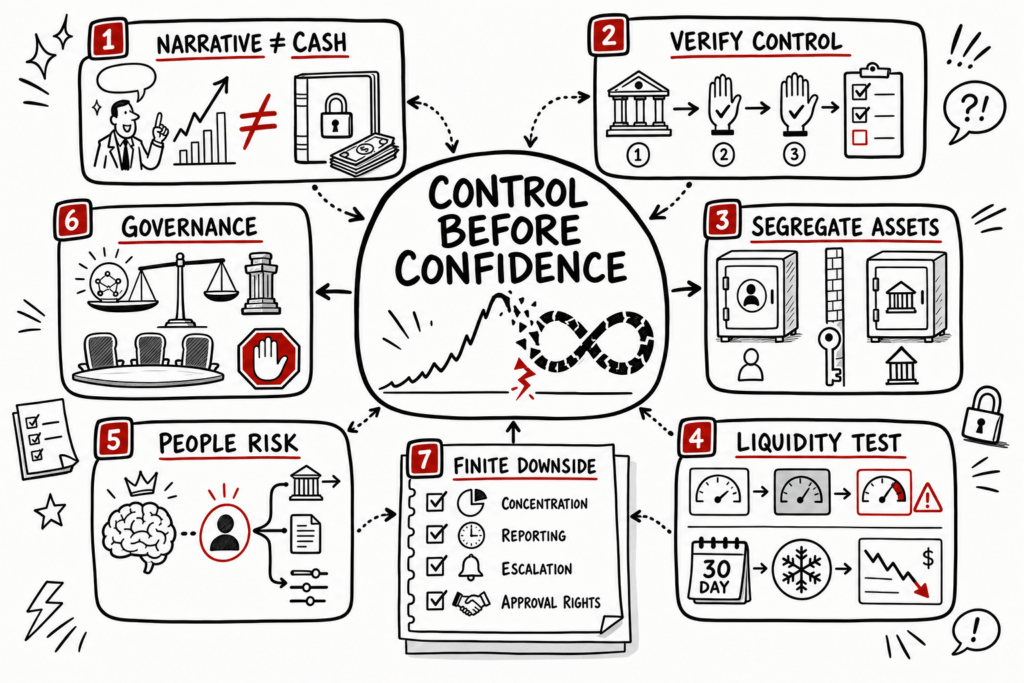
What Is the Going Infinite Summary for Real Estate and Family-Office Leaders?
This Going Infinite summary considers what Michael Lewis’s portrait of a fast-scaling crypto founder can teach real-estate principals, family-office leaders, and alternative-asset allocators about the gap between confidence and control. The book is a narrative and a study of people-risk; it is not a technical crypto manual, an investment recommendation, or a substitute for legal, accounting, or regulatory diligence.
Its practical use is to ask who controls cash, whether assets are segregated, what reporting rights exist, and how a vehicle would operate through a liquidity interruption. Those questions belong in a broader diligence process, not in a verdict drawn from one book.
What Going Infinite Is: A Spoiler-Free Overview
Published in 2023, Going Infinite is Michael Lewis’s character-driven account of a founder, a fast-scaling crypto enterprise, and the culture around both. Lewis focuses less on teaching blockchain mechanics than on unusual talent, confidence, incentives, and the way complex markets become personal stories.
That makes the book relevant beyond crypto. When markets reward speed, novelty, and access, leaders can mistake social proof for institutional quality. Paper wealth can look like liquidity, a polished interface can look like a control environment, and a compelling mission can make ordinary diligence feel disloyal.
The publisher page for Going Infinite positions the book as a journey into the mind and rise of an unconventional founder. That framing matters: it is primarily a close portrait, not an enforcement record or a complete reconstruction of every event.
Core Idea: Founder Psychology Meets Institutional Risk
The central leadership question is not whether unconventional founders are good or bad. It is whether an organization can turn useful traits such as speed, conviction, and tolerance for uncertainty into durable value without allowing them to bypass controls.
When attention and capital arrive faster than operating maturity, a founder can receive reinforcement without meaningful correction. Decision velocity becomes a status signal, complexity makes challenge harder, and proximity to apparent success is treated as evidence that the system is sound. Purpose can guide an organization, but it cannot replace reconciliations, approval limits, board challenge, or clear asset ownership.
Best Takeaways: Going Infinite Leadership and Strategy Lessons
1. Narrative strength is not balance-sheet strength
A founder may be persuasive, analytically gifted, and well connected while the enterprise remains fragile. Separate claims about market size, future value, and social impact from evidence about current cash, liabilities, asset ownership, and withdrawal obligations.
2. Access is not verification
Celebrity adjacency, prestigious advisers, and elite networks can lower everyone’s willingness to ask basic questions. They do not prove that assets exist, controls work, or related-party transactions are governed appropriately. Network endorsement is context, not diligence.
3. Liquidity must be tested, not assumed
Quoted values and internal marks can create a liquidity illusion. Ask what could actually be sold, by whom, at what discount, and within what period. For an explicitly illustrative committee exercise, model a decline in asset values alongside a defined period in which refinancing or expected redemptions cannot occur; label every assumption and do not present the scenario as a market forecast.
4. Counterparty exposure includes people and process
Counterparty risk is not only a question of financial capacity. If one person can move money, override policy, alter records, and define the narrative, the exposure is also a governance risk. Map who can initiate, approve, reconcile, and report each material action.
5. Intelligence does not cancel stewardship
Brilliant reasoning can explain why ordinary rules appear inefficient. Stewardship asks who bears the loss if that reasoning is wrong. That is a useful question for anyone responsible for limited-partner, client, or family capital.
Relevance to Real Estate Syndication and Family Offices
The parallels to real assets are practical. Property syndications, proptech platforms, tokenized ownership structures, fractional investments, and cross-border raises can combine persuasive sponsors with hard-to-verify operating arrangements.
Real-estate syndication diligence should extend beyond property underwriting. Confirm where investor funds are held, who authorizes wires, how distributions are calculated, what affiliate relationships exist, and whether property-level debt can create exposure elsewhere. Family-office diligence should map concentration across sponsors, lenders, administrators, valuation sources, and banking relationships; several investments may share one hidden dependency.
Where It Falls Short: A Going Infinite Review
The book’s strength—unusual proximity to its central subject—is also its limitation. Narrative momentum can give a founder’s logic and personality substantial space relative to responsibility and institutional harm. The book is strongest as a study of people-risk, organizational permission, and the seduction of apparent inevitability.
It is not the best single source for technical crypto mechanics, forensic accounting, or a comprehensive legal timeline. Read the narrative alongside audited documents, primary reporting, applicable regulatory material, and qualified advice. Ask it to show how capable people normalize weak boundaries, not to supply a final finding.
How to Apply It
Turn the book’s questions into an investment-committee checklist:
- Cash control: Who can initiate, approve, and reconcile a wire? Set independent approvals above a defined threshold.
- Asset segregation: Are client or limited-partner assets separated from sponsor and affiliate assets in law and practice?
- Independent evidence: Which balances, valuations, and ownership claims are confirmed by third parties?
- Related parties: What fees, loans, guarantees, or service agreements involve founders or affiliates?
- Liquidity stress: What happens if refinancing is late, exits freeze, or expected distributions stop?
- Governance: Can the board block management, or does it merely advise?
- Key-person risk: Can reporting, banking, and operations continue if the founder is unavailable?
Translate upside rhetoric into finite downside protections: concentration limits, reporting deadlines, approval rights, and escalation triggers. If a sponsor treats basic questions as disloyalty, that response is itself diligence data.
Who Should Read It?
Read Going Infinite if you allocate family capital, underwrite sponsors, lead a syndication, structure joint ventures, or build governance inside a fast-growing venture. It is especially useful for professionals who analyze assets carefully but assess founder psychology and organizational culture less systematically.
It is worth reading as a vivid case study that sharpens questions about custody, control, trust, and rapid capital formation. Deprioritize it when the immediate need is trading instruction, technical blockchain education, or definitive legal analysis.